7 Mortgage Myths That Quietly Cost BC Buyers Money

Rabinder Dhillon • June 15, 2026

A lot of what people believe about mortgages is out of date or simply untrue, and those myths can cost real money or delay a purchase for years. Here are seven of the most common ones I hear, and the plain truth behind each.


Myth 1: You Need 20 Percent Down to Buy a Home

This one keeps more people renting than any other. In reality, you can buy with as little as 5 percent down on the first 500,000 dollars of the price. With less than 20 percent down, your mortgage is simply insured, which is completely normal and gives you access to the best rates. Many buyers are ready years before they realize it.


Myth 2: Your Bank Gives You the Best Deal

Your bank can only offer its own products. As a broker, I compare many lenders, from major banks to credit unions and other lenders, to find the best fit for you. Loyalty to one institution often costs more than it saves.


Myth 3: The Lowest Rate Is Always the Best Mortgage

A low rate attached to the wrong terms can cost you far more over time. Restrictive penalties, limited prepayment privileges, and poor flexibility can quietly outweigh a small rate difference. The best mortgage is the one that fits your whole situation, not just the number on the sign.


Myth 4: Using a Mortgage Broker Costs You Money

For most residential mortgages, my services are free to you. The lender pays me when your mortgage funds, so you get access to many lenders and my guidance at no direct cost, rather than being limited to a single bank.


Myth 5: A Pre-Qualification Is the Same as a Pre-Approval

They are very different. A pre-qualification is a quick estimate with nothing verified. A pre-approval involves reviewing your documents and credit and comes with a rate hold. When you make an offer, only one of them carries real weight.


Myth 6: If You Are Self-Employed, You Cannot Get a Mortgage

Not true at all. Self-employed simply means your income needs to be presented the right way, and there are lenders and programs built specifically for business-for-self borrowers. Your smart tax planning does not have to work against you.


Myth 7: You Should Always Renew With Your Current Lender

Signing the renewal your lender mails you is rarely their best offer. Your renewal is a chance to compare the whole market and often improve your rate or terms. It takes a quick conversation to find out whether you can do better.


The Truth Is Usually Good News

Most mortgage myths make homeownership feel harder or further away than it really is. When you have the facts, the picture is often far more encouraging. I got into this work because I believe knowledge is power, and the more you understand, the fewer of these myths cost you money.


Heard something about mortgages that worried you? Ask Rabinder Dhillon and let's separate fact from fiction, with no pressure.
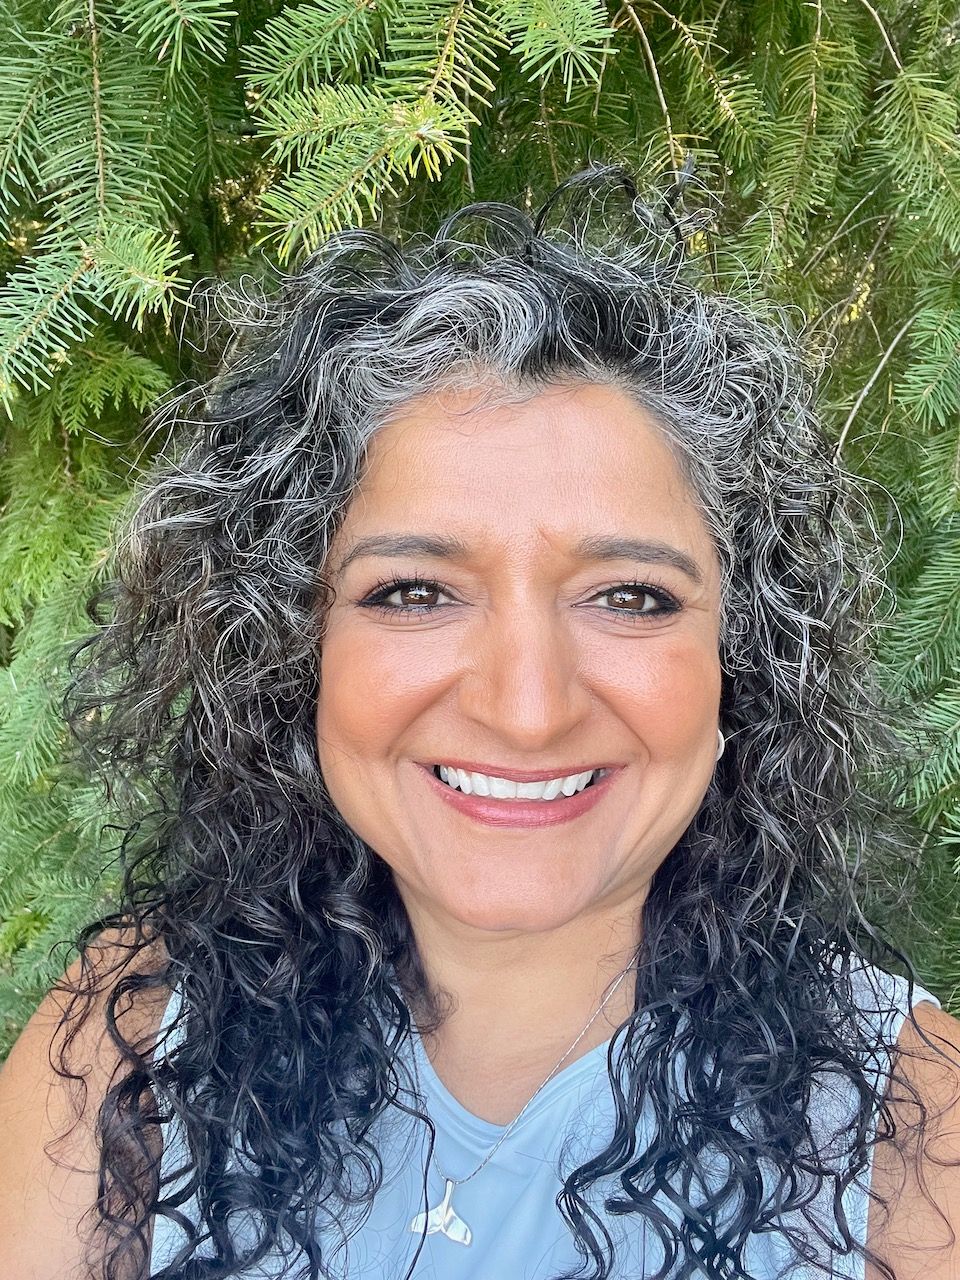
RABINDER
MORTGAGE BROKER

LET'S CONNECT
By Rabinder Dhillon • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Rabinder Dhillon • October 21, 2026
Your Lender Is Not Obligated to Renew Your Mortgage Many homeowners assume that if they’ve made every mortgage payment on time, their lender is automatically required to renew their mortgage at the end of the term. That’s a common belief—but it isn’t true. When you sign a mortgage, you’re agreeing to a contract for a specific term . Once that term ends, the lender has the legal right to either renew the mortgage or call the loan . There is no obligation to offer a renewal. In practice, most lenders do renew mortgages—but certain situations can prevent that from happening. Reasons a Lender May Decline to Renew A lender may choose not to renew if: Mortgage payments were missed during the term A bankruptcy or consumer proposal has occurred There is a separation or divorce Employment or income has changed A borrower on the mortgage has passed away The lender no longer prefers the property’s location or market The lender is no longer licensed to lend in Canada Even one of these factors can change how a lender views the risk. Why This Matters Because renewal is not guaranteed, waiting until the last minute can put you in a difficult position. Understanding this reality early gives you time and control. How to Protect Yourself at Renewal The best approach is to be proactive. Ideally, you should begin reviewing your options 120 days before your mortgage term ends . This gives you enough time to explore alternatives and make informed decisions—rather than reacting under pressure. Even if your current lender offers a renewal, that’s just one option , not automatically the best one. The lender that was right for you years ago may no longer offer the most competitive rate, terms, or flexibility today. The goal at renewal isn’t convenience—it’s reducing your total cost of borrowing and choosing terms that align with your current situation. Why Work With an Independent Mortgage Professional Working with an independent mortgage professional ensures someone is advocating for you , not the lender. Instead of being limited to one set of products, you can compare options across multiple lenders and choose the solution that best protects your interests. Final Thoughts Whether your lender is offering a renewal or not, the smartest move is to review all your options before signing anything. If your mortgage is coming up for renewal—or if you want to plan ahead—feel free to connect anytime. I’d be happy to help you protect your options and make a confident decision.